
Moving into a new rental property—whether it is a high-rise studio apartment in Chicago, a suburban townhome in Dallas, or a shared duplex in Atlanta—marks an exciting chapter. However, amidst the flurry of signing lease agreements, paying security deposits, and arranging moving logistics, millions of American tenants harbor a dangerous financial misconception: they believe that because their landlord carries insurance on the building, their personal belongings and personal financial liability are protected as well.
This assumption is fundamentally false. Under United States real estate and property casualty laws, a property owner's commercial policy strictly covers the physical structure—the framing, exterior siding, foundational concrete, and roof. It provides exactly zero dollars and zero cents of coverage for your furniture, electronics, designer clothing, or personal liability if an unexpected disaster strikes. If a fire starts in a neighboring unit or an upstairs tenant's plumbing ruptures, you alone bear the financial burden of replacing everything you own.
Landlord master policies protect the landlord's structural equity. Only an individual HO-4 tenant policy protects your personal net worth and property.
Fortunately, renters insurance is one of the most affordable and comprehensive risk-management tools in personal finance. For an average national cost of approximately $15 to $18 per month—less than the price of a single takeout dinner—a standard renters policy provides tens of thousands of dollars in property replacement, hundreds of thousands of dollars in legal defense coverage, and emergency temporary living assistance. In this exhaustive guide, we will unpack the mechanics of renters insurance, analyze the three foundational coverage pillars, audit the 16 statutory covered perils, explore critical exclusions, examine real-world claim calculations, and provide an actionable roadmap for choosing the right policy.
1. The Anatomy of an HO-4 Policy: The Three Foundational Pillars
In the property and casualty insurance industry, a standard renters insurance contract is technically classified as an HO-4 policy form (Homeowners Form 4). Unlike homeowner policies that must bundle structural dwelling coverage (Coverage A) and other detached structures (Coverage B), an HO-4 policy is streamlined exclusively for tenants. It is anchored by three interrelated coverages that work together to shield you from catastrophic financial losses.
Pillar 1: Personal Property Coverage (Coverage C)
Coverage C constitutes the core of your policy's tangible protection. It covers the repair or replacement cost of your personal belongings if they are damaged, destroyed, or stolen due to an unexpected, covered event. Many renters believe they do not own enough to warrant insurance. However, when you perform a rigorous accounting of every garment in your wardrobe, every kitchen utensil, every piece of furniture, and every piece of technology, the cumulative value routinely surpasses $25,000 to $40,000.
Under Coverage C, your possessions are safeguarded across multiple categories:
- Electronics & Digital Assets: Laptops, desktop computers, smartphones, tablets, 4K smart televisions, audio equipment, gaming consoles, and smart home appliances.
- Living Room & Bedroom Furniture: Sectional sofas, recliners, entertainment consoles, mattresses, box springs, bed frames, dressers, dining sets, and area rugs.
- Clothing & Personal Apparel: Business attire, winter outerwear, designer footwear, athletic gear, accessories, and luggage.
- Kitchenware & Housewares: High-end cookware sets, espresso machines, blenders, dishware, cutlery, and pantry goods.
- Sports, Hobbies & Musical Equipment: Bicycles, camping gear, musical instruments, hobby supplies, and books.
Crucially, Coverage C is not restricted to items located physically inside your rented apartment. Under standard ISO policy language, Coverage C includes worldwide off-premises coverage. If your laptop is stolen from the backseat of your parked car, if your backpack is snatched in a library, or if your luggage vanishes from an international hotel room in Europe, your renters policy responds to cover the loss (subject to applicable off-premises sub-limits).
Pillar 2: Personal Liability Protection (Coverage E)
While replacing a damaged laptop is an inconvenience, facing a major civil lawsuit can destroy your financial future. Personal liability coverage protects you when you, a resident family member, or even your pet are held legally responsible for causing bodily injury to a third party or property damage to someone else's property.
Consider the staggering costs associated with modern civil litigation and healthcare in the United States:
- Accidental Slip-and-Fall Incidents: A guest trips over an uneven rug or an exposed extension cord in your living room, suffers a fractured hip or concussion, and incurs $65,000 in emergency room surgeries and rehabilitation therapy. Your liability policy covers their medical expenses.
- Tenant-Caused Structural Water Damage: You step away while running a bath, the tub overflows, and water permeates through the subfloor, ruining the custom drywall, crown molding, and antique furniture of the apartment below you. The downstairs tenant and the building owner's commercial insurer demand $35,000 in restitution. Your liability coverage pays for their damages.
- Legal Defense & Attorney Retainers: In the US legal system, defending against even a completely frivolous lawsuit costs an average of $350 to $650 per hour in attorney fees. Under Coverage E, your insurance company has an independent Duty to Defend. They will assign and pay for legal counsel to represent you in court, and these legal defense fees are paid in addition to your policy limits.
Most basic policies provide a default limit of $100,000 in liability protection. However, elevating this threshold to $300,000 or $500,000 usually costs a mere $12 to $18 per year in additional premium, representing one of the highest-value upgrades in the entire insurance industry.
Pillar 3: Additional Living Expenses / Loss of Use (Coverage D)
Imagine waking up at 3:00 AM to the blaring sound of building fire alarms. An electrical fire in a first-floor utility room fills the entire complex with toxic smoke and burns through municipal power lines. City building inspectors immediately condemn the property as uninhabitable for the next six months while remediators repair structural framing and replace electrical wiring.
Where do you live tomorrow? How do you afford three months of extended-stay hotel bills, daily restaurant dining without a kitchen, emergency pet boarding, and storage locker rentals? Your landlord has no legal obligation to pay for your hotel stay.
Coverage D—commonly known as Loss of Use or Additional Living Expenses (ALE)—covers the net difference between your normal cost of living and the emergency expenses required to maintain your standard of living while displaced by a covered peril. Reimbursable items include:
- Temporary hotel room charges or short-term apartment lease premiums.
- Restaurant meal expenditures that exceed your ordinary monthly grocery budget.
- Emergency pet boarding costs if your temporary lodging does not allow animals.
- Storage unit rental fees to safeguard surviving furniture during building restoration.
- Increased transportation and fuel costs if your temporary home requires a longer commute to work.
2. The 16 Named Perils: When Does Coverage Trigger?
Most standard renters insurance policies operate on a named-perils basis for personal property. This means that for a claim to be approved and reimbursed, the damage must be directly caused by one of the specific perils formally enumerated in the policy contract. The standard ISO HO-4 policy enumerates 16 statutory perils:
| Peril Number & Name | Legal & Practical Definition | Everyday Real-World Example |
|---|---|---|
| 1. Fire or Lightning | Direct combustion, electrical fires, and atmospheric lightning strikes. | Kitchen grease fire destroys cabinetry and living room furniture. |
| 2. Windstorm or Hail | Atmospheric wind damage, hurricane winds, and hail impact. | Hail shatters an apartment window and ruins interior electronics. |
| 3. Explosion | Sudden catastrophic pressure release from gas lines, water heaters, etc. | A natural gas leak in the basement utility room causes a blast. |
| 4. Riot or Civil Commotion | Property destruction arising from public unrest or assembly. | Civil unrest in an urban corridor results in broken doors and property loss. |
| 5. Aircraft Damage | Physical contact from falling planes, helicopters, or aircraft debris. | Debris falling from a commercial flight damages an apartment complex. |
| 6. Vehicles | Physical impact from automobiles or commercial trucks. | An out-of-control driver crashes through your first-floor patio sliding door. |
| 7. Smoke | Sudden and accidental smoke discharge, including soot permeation. | A severe fire in the apartment below ruins all clothing with toxic soot. |
| 8. Vandalism / Malicious Mischief | Deliberate third-party destruction or defacement of property. | Intruders break into your apartment and destroy your television and art. |
| 9. Theft | Unlawful taking of personal property (on-premises or off-premises). | Burglars force open your deadbolt and steal jewelry and laptops. |
| 10. Falling Objects | External objects striking the building and damaging interior contents. | A massive tree branch crashes through the roof during a thunderstorm. |
| 11. Weight of Ice, Snow, or Sleet | Structural collapse or damage resulting from frozen precipitation load. | Heavy blizzard snow causes the ceiling to collapse into your bedroom. |
| 12. Accidental Discharge of Water | Sudden rupture of internal plumbing, heating, or AC systems. | The pressurized copper water supply line behind the refrigerator bursts. |
| 13. Sudden Tearing Apart / Cracking | Rupture of steam, hot water heating, or air conditioning systems. | A boiler system expands and cracks, discharging boiling water. |
| 14. Freezing of Plumbing | Plumbing rupture caused by freezing conditions (requires adequate heat). | A sub-zero arctic blast freezes exterior wall pipes, which split open. |
| 15. Sudden Electrical Current Surge | Artificially generated electrical surges damaging wired electronics. | A power grid malfunction sends a surge that fries a high-end audio setup. |
| 16. Volcanic Eruption | Airborne shockwaves, ash discharge, and volcanic particulate matter. | Ash and particulate from a volcanic event damages property. |
3. What Renters Insurance Does NOT Cover: Critical Exclusions
Understanding what an insurance contract excludes is just as important as knowing what it covers. A common cause of claim frustration is assuming a policy protects against every conceivable peril. Standard renters insurance contracts strictly exclude the following events:
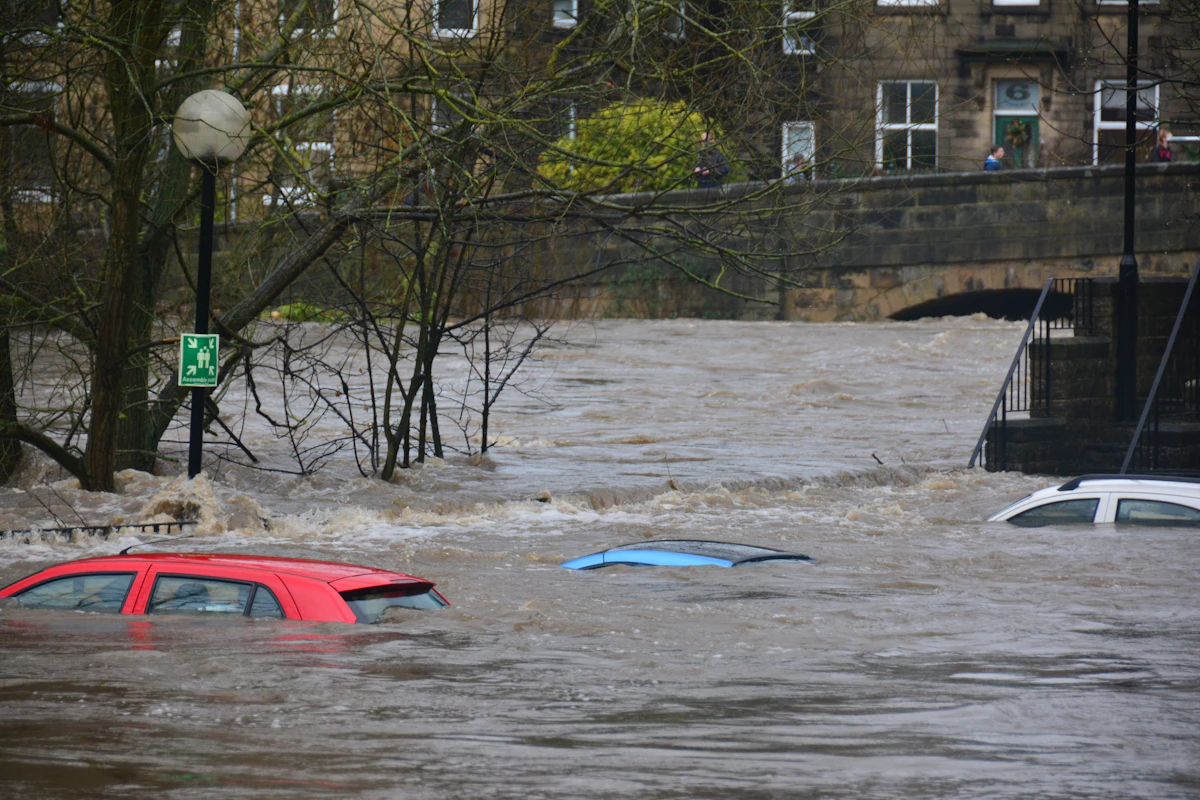
Overland floodwaters and natural rising water are universally excluded from standard HO-4 policies.
1. Overland Flooding and Storm Surge
No standard renters insurance policy in the United States covers natural flooding. If a local river overflows its banks, a tropical storm brings severe storm surges into your garden-level apartment, or heavy rain pools in your street and seeps through your patio door, your standard policy pays $0.
The Solution: If you reside in a FEMA-designated flood zone or rent a ground-level or basement unit, you must purchase a standalone National Flood Insurance Program (NFIP) policy or a private tenant flood rider. These policies specifically cover tenant contents up to $100,000 against rising floodwaters.
2. Earthquakes, Tremors, and Landslides
Earth movement—including geological fault ruptures, tremors, mudslides, and sinkholes—is explicitly excluded from standard policies. In high-risk seismic regions like California, Washington State, Oregon, and the New Madrid Seismic Zone, an earthquake could destroy your furniture and electronics without triggering basic coverage.
The Solution: You can add an optional Earthquake Endorsement to your existing policy, or in California, purchase a separate tenant policy through the California Earthquake Authority (CEA).
3. Pest Infestations (Bedbugs, Rodents, Termites)
Insurers classify insect and rodent infestations as long-term property maintenance issues rather than sudden and accidental perils. If bedbugs infest your mattress or mice chew through your television cords, your renters insurance policy will not reimburse you for pest remediation, furniture disposal, or hotel stays.
4. Normal Wear and Tear or Gradual Deterioration
Insurance is designed to guard against sudden catastrophes, not the natural aging process. If an office chair breaks because the hydraulic cylinder wore out after six years of use, or if a laptop slows down due to an aging battery, insurance adjusters will deny the claim as normal wear and tear.
5. Unlisted Roommates' Possessions
Unless an individual is a legally married spouse, a minor child, or explicitly named as an additional insured on the policy declaration page, their personal property and legal liability are completely excluded. If your roommate's gaming PC is stolen from the living room, your policy cannot pay for it.
4. The Crucial Valuation Choice: Actual Cash Value (ACV) vs. Replacement Cost Value (RCV)
When you fill out an online application for renters insurance, you will encounter a pricing question that changes the financial payout of every future claim: Do you want Actual Cash Value (ACV) or Replacement Cost Value (RCV)?
Understanding the difference between these two valuation methods is essential to avoid surprises during a claim settlement:
Mathematical Breakdown: The 4-Year-Old Entertainment System
Imagine a grease fire destroys your living room, including a high-end 65-inch 4K OLED television purchased four years ago for $2,000. You carry a standard $500 deductible.
Under Actual Cash Value (ACV):
The insurance company calculates depreciation based on an average useful life of 5 years (20% depreciation per year). At four years old, the television has depreciated by 80% ($1,600). The current market value of your TV is determined to be $400.
$400 Market Value - $500 Deductible = $0 Payout
Because the depreciated value is lower than your deductible, the insurer pays nothing. You must fund the entire replacement out of pocket.
Under Replacement Cost Value (RCV):
The insurer disregards depreciation and reviews current retail pricing for a brand-new, modern equivalent 65-inch OLED TV, which currently retails for $1,800.
$1,800 Replacement Cost - $500 Deductible = $1,300 Payout
The insurer issues a check for $1,300, allowing you to walk into an electronics retailer and purchase a brand-new television immediately.
Choosing Replacement Cost Value typically increases your annual premium by just 10% to 15% (an extra $1.50 to $2.50 per month). Never settle for an ACV policy simply to save a couple of dollars a month.
5. Case Study: Real-World Claim Settlement Breakdown
To see how an HO-4 policy responds during a multi-faceted disaster, consider the real-world case of Sarah M., a graphic designer renting a second-floor apartment in Atlanta, Georgia.
Case Summary: The Frozen Pipe Failure
The Incident: During an unusual sub-freezing winter event, an interior water pipe located inside the wall of the third-floor apartment burst. Pressurized water cascaded through the floorboards for four hours while Sarah was at work. Her ceiling partially caved in, soaking her work computer, furniture, wardrobe, and custom art portfolio.
Displacement: Municipal building inspectors red-tagged the unit, mandating industrial dry-out fans, drywall removal, and ceiling framing repairs that required 45 days to complete.
Sarah's Policy Limits: Personal Property (RCV): $40,000 | Loss of Use: $12,000 | Liability: $300,000 | Deductible: $500.
Here is how Sarah's insurance claims adjuster processed her claim line-by-line:
| Claim Category | Itemized Losses & Invoices | Adjuster Calculation | Net Settlement |
|---|---|---|---|
| Personal Property (Tech) | MacBook Pro, 32" 4K Monitor, Audio Interface | Current retail replacement value | $4,850.00 |
| Personal Property (Furniture) | Waterlogged mattress, upholstered couch, desk | Full replacement equivalent quotes | $3,600.00 |
| Personal Property (Wardrobe) | Damaged coats, business suits, shoes | Documented inventory itemization | $2,450.00 |
| Loss of Use (Lodging) | 45 nights at an extended-stay business hotel | 45 nights × $110/night | $4,950.00 |
| Loss of Use (Meals) | Restaurant dining over normal grocery budget | $35/day excess meal expense documented | $1,575.00 |
| Gross Approved Loss | Total Property & Additional Living Expenses | -- | $17,425.00 |
| Less Policy Deductible | Personal Property Deductible | Subtracted from property check | -$500.00 |
| TOTAL NET INSURANCE SETTLEMENT | Direct Deposit / Payout to Insured | -- | $16,925.00 |
Without an active renters policy, Sarah would have been forced to absorb nearly $17,000 in personal debt while trying to navigate temporary relocation on her own.
6. Step-by-Step Action Plan: How to Buy the Right Policy in 5 Steps
Purchasing an HO-4 policy is straightforward. Follow these five operational steps to bind comprehensive coverage without overpaying:
- Conduct a Digital Video Walkthrough: Before requesting quotes, spend ten minutes walking through your apartment with your smartphone camera. Open every closet, record all electronics, and pan across furniture. Upload this video to secure cloud storage (Google Drive or Dropbox). If a total disaster occurs, this video serves as evidence of ownership.
- Select Replacement Cost Value (RCV): Ensure the quote engine specifies RCV rather than Actual Cash Value for Coverage C. This single toggle guarantees you can replace lost items at current retail prices.
- Elevate Personal Liability to at Least $300,000: Do not stick with the default $100,000 limit. The price difference between $100k and $300k is typically less than $1.25 per month.
- Optimize Your Deductible: If you maintain at least $1,000 in an emergency savings account, choose a $500 or $1,000 deductible rather than $250. This saves you 10% to 15% on your monthly premium.
- Bundle with Your Auto Insurance Carrier: Check rates with the insurance company that currently covers your car. Multi-policy bundling discounts frequently reduce your auto insurance premium by enough to cover the cost of your renters policy.
7. In-Depth Frequently Asked Questions (FAQ)
Does renters insurance cover my roommate?
Generally, no. Standard insurance contracts define the named insured as you, your legal spouse, and resident relatives by blood or adoption. An unrelated roommate is not automatically covered. If their laptop is stolen or they cause a kitchen fire, your policy will not defend them or replace their belongings. While some carriers allow you to add a roommate as an additional named insured, doing so dilutes your property coverage limits and means claim checks are issued in both names. Every adult tenant should purchase an independent policy.
Does renters insurance cover damage caused by my dog or cat?
It depends on the type of damage. If your dog bites a guest or another dog at the park, your personal liability coverage typically pays their medical and veterinary bills (provided your carrier does not exclude your dog's breed). However, renters insurance never covers property damage caused by your own pet to your own rental. If your cat scratches your carpet or your dog chews through baseboards, that is considered a pet deposit matter between you and your landlord.
What happens if I accidentally cause damage to the rental building?
If you are legally liable for causing accidental damage to the landlord's property—such as starting a grease fire on your stove or causing a sink overflow that damages flooring—your personal liability coverage pays for the landlord's structural repair costs, protecting you from personal subrogation lawsuits.
Can my landlord force me to buy renters insurance?
While there is no federal or state statutory law mandating renters insurance, it is completely legal for private landlords and property management firms to require a policy as a condition of signing the lease. If you refuse to maintain an active policy, your landlord can legally deny your application or issue a lease violation notice.
Does renters insurance cover my items inside my vehicle?
Yes. Comprehensive car insurance only pays for physical damage to the automobile itself (such as a broken window). Personal items left inside the car—like laptops, sunglasses, or gym bags—are covered under the off-premises personal property clause of your renters insurance policy, subject to your renters deductible.
Summary: Final Verdict and Next Steps
Renters insurance offers some of the best value in personal finance. For approximately fifty cents a day, an HO-4 policy protects your personal property from 16 named perils, shields your life savings from personal liability claims, and guarantees a roof over your head if an unexpected catastrophe forces you from your home.
Do not wait for a burst pipe or building fire to reveal the gaps in your financial plan. Take a smartphone inventory of your apartment today, request quotes from at least three reputable carriers, and ensure you have an active policy in place.
Disclaimer: This article is for educational and informational purposes only and does not constitute licensed legal, financial, or insurance advice. Policy language, covered perils, exclusions, and statutory limits differ by carrier and state jurisdiction. Always review your official policy declaration page and consult a licensed insurance producer before purchasing.


0 Comentarios